YEREVAN, October 26. /ARKA/. Armenia’s corporate bond market is entering a new stage of development, expanding opportunities for businesses to secure financing while offering investors an alternative to bank deposits. The market’s continued growth, however, will depend on investor confidence, the quality of issuers, liquidity in the secondary market, and the maintenance of incentive measures.
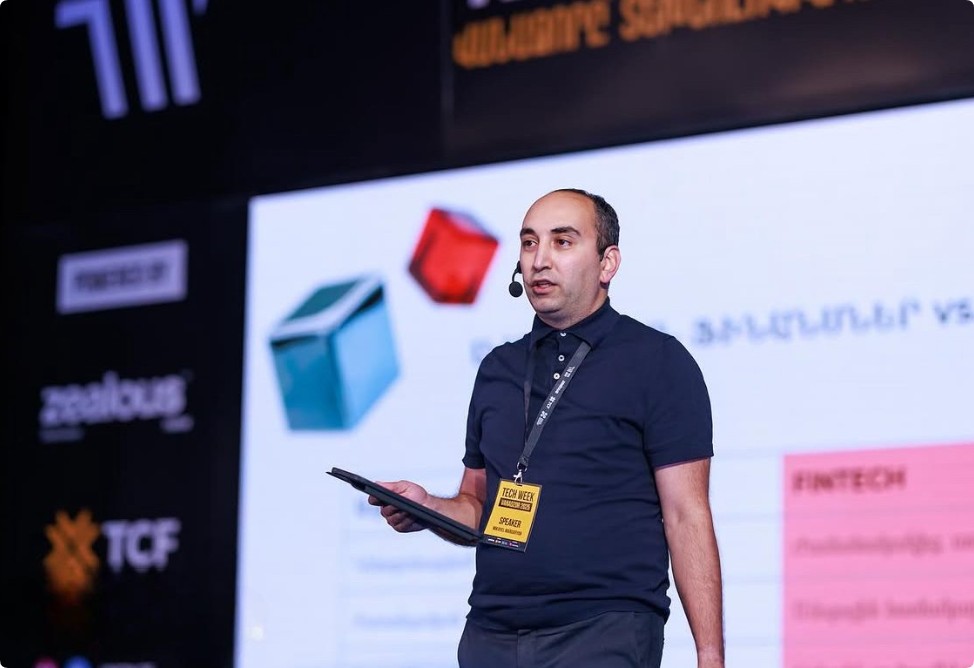
In an exclusive interview with the ARKA news agency, Mikayel Margaryan, Chairman of the Board and CEO of the investment firm CUBE Invest, discussed the prospects for Armenia’s corporate bond market, the level of interest from businesses and investors in this instrument, as well as the associated risks and limiting factors. He also addressed topics such as attracting foreign investment, tax incentives, and the digitalization of investment services.
ARKA — Can it be said that Armenia’s corporate bond market is entering a new stage of development? What is driving its growth?
M. Margaryan — Yes, such a transition is underway. The development of a capital market is typically envisioned as a pyramid: starting from the currency and money markets, moving to government bonds, then corporate bonds, and finally, equities. Currently, Armenia is at the fourth level the stage of corporate bond market development.
The government bond market remains the most developed segment. The state regularly issues both dram-denominated securities and Eurobonds; notably, over the past five years, investment by international investors in dram-denominated government bonds has grown approximately six- to sevenfold.
The corporate bond market is also seeing significant development. This is driven by an increased inflow of capital into the country, growing public interest in investment instruments, and a desire among companies to diversify their funding sources beyond traditional bank loans. The strengthening of the national currency against the US dollar has served as an additional factor making dram-denominated bonds more attractive.
Government incentives also play an important role. Tax exemptions on income from bonds traded on the Armenia Securities Exchange are in place until the end of 2027. Furthermore, a support program for issuers in the real sector which provided subsidies for bond issuance costs and coupon payments, subject to specific conditions was in effect starting in 2023.
This program concluded on September 1, 2026. It succeeded in attracting new issuers to the market, and discussions are now underway regarding its potential transformation into a new format. It is quite possible that relevant decisions could emerge as early as 2027.
ARKA — To what extent has the range of issuers expanded? Which sectors are entering the market?
M. Margaryan — We are seeing an increasing number of sectors represented in the corporate bond market. Since November 2025, we have placed bond issues totaling approximately 9 billion drams, all of which have been fully subscribed. The vast majority of these securities are denominated in the national currency.
The issuers include companies from the agricultural and construction sectors, the food industry, and IT. We have also facilitated bond issues for the Dalan technology park and two companies in the fashion industry Freestyle and ML Fashion.
This demonstrates that corporate bonds are becoming a financing tool for businesses across a wide variety of sectors.
ARKA — Which sectors are in highest demand among investors?
M. Margaryan — I wouldn’t single out any specific sectors. At this stage, what matters more is the level of trust in the issuer and the quality of the bond issue itself.
Over nearly a decade of operation, we have made trust one of our top priorities. Before offering a new product to our clients, we take great care to vet it and assess the associated risks. Every issuance undergoes a comprehensive analysis.
We have declined to work with companies that failed to meet our standards for transparency, governance, and financial reporting. In such cases, we advise them to first address these shortcomings and establish sound corporate governance before attempting to enter the public market.
ARKA — What should a company consider if it plans to raise capital through bonds for the first time?
M. Margaryan — First and foremost, the issuer must fully grasp the responsibility they are taking on. Issuing bonds is not merely a way to secure funding; it represents a commitment to investors and marks a significant milestone in the company’s development.
To date, there have been no issuer defaults in our market, and it is crucial for all participants to do their utmost to maintain this track record. In a small market, a default could deal a severe blow to investor confidence.
A company must be prepared to disclose information, ensure transparent financial reporting, adhere to corporate governance principles, appoint independent board members, and implement a robust risk management system.
Sometimes, businesses view these requirements as an additional burden. In the long run, however, they help a company improve its management, assess risks more effectively, and enhance the quality of its decision-making.
ARKA — Who is the primary buyer of corporate bonds in Armenia today? Why are individuals choosing them over bank deposits?
M. Margaryan — In terms of investment volume, institutional investors, including pension funds play the leading role. As their assets grow, so does the need for new instruments that allow for portfolio diversification and generate returns.
In terms of the number of investors, individuals predominate. There is a particularly notable interest in bonds denominated in Armenian drams.
One key factor is the yield. For instance, if a bank deposit offers an annual interest rate of 9.5%, while a corporate bond offers 12.5%, the difference three percentage points represents an additional risk premium. It is important to note that bank deposits are protected by a guarantee system (subject to statutory conditions), whereas corporate bonds carry the risk that the issuer may fail to meet its obligations.
ARKA — How can a private investor assess an issuer’s reliability, rather than focusing solely on the interest rate?
M. Margaryan — Not every private investor has the capacity to independently review a multi-page prospectus or conduct a comprehensive financial analysis. However, there are a few fundamental questions that can help form an initial understanding of the risks involved.
How much does the company earn? What are its liabilities? How does its debt compare to its EBITDA (earnings before interest, taxes, depreciation, and amortization)? From what revenue sources does the issuer intend to service its debt and repay the principal investment?
For example, if a company plans to raise 10 billion drams through a bond issuance, but its annual profit is only 500 million drams, an investor should consider exactly where the funds for repayment will come from and the timeline over which the company will be able to return the capital. In a prospectus, an issuer must disclose the purposes for which funds are being raised, business development plans, and expected financial results. It is important to assess how realistic these plans are and whether their implementation will enable the issuer to meet its obligations to investors.
However, a private investor does not necessarily have to conduct this entire analysis on their own. They can seek advice from a professional market participant to obtain clarification regarding the terms of the issuance and the associated risks.
ARKA — Low liquidity in the secondary market remains a constraint. What needs to be done to make bond trading more frequent?
M. Margaryan — The secondary market has become more active in recent years. For instance, we act as market makers for nearly 20 bond issues and conduct daily trades in the securities for which we provide quotes this includes both our own issues and bonds from certain banks.
That said, market depth and liquidity remain limited. Nevertheless, when compared to some neighboring countries and states in Central Asia, the situation in Armenia appears better.
One way to boost liquidity is to engage two market makers for large bond issues. Under the rules of the Armenia Securities Exchange, a market maker is required to provide daily quotes equal to 1% of the issue size, capped at 100 million drams (or the equivalent in foreign currency). Consequently, for an issue totaling 30 billion drams, the mandatory quote volume in monetary terms remains the same, while its share of the total issue size becomes significantly less than 1%.
This can create some inconvenience for large investors. If an issue has two market makers, each can provide quotes for up to 100 million drams, which increases the potential market depth.
This practice is already being applied to certain issuers, including ESA, Team Telecom, and the perpetual bonds of Ameriabank.
ARKA — To what extent does the regulatory framework foster market development? Should the requirements for issuers be simplified?
M. Margaryan — Overall, the current regulatory framework functions quite effectively, though there is still room for optimization, particularly for smaller companies. A distinct, regulated form of crowdfunding has recently emerged, allowing smaller companies to raise capital without undergoing the full range of procedures required for a traditional public securities offering.
Given the growth of the IT sector, it is worth considering the creation of additional, intermediate instruments with more flexible requirements. Such discussions are currently underway, including with the stock exchange.
ARKA — What measures could increase the number of high-quality securities offerings and strengthen market confidence?
M. Margaryan — The Armenia Securities Exchange is looking at the experience of its parent company, the Warsaw Stock Exchange, to create additional opportunities for smaller issuers.
One promising avenue is to simplify the listing process on the Armenian exchange for securities that are already traded on international platforms. This could help foster the development of the domestic market.
It is also worth considering the extension of tax incentives. These help develop the market, and the income earned by investors can flow back into the economy through spending and further investment.
Another key factor is digitalization. We have launched a mobile app, CUBE Invest, which allows individuals to conduct transactions in both international and local markets, as well as exchange foreign currency.
Such an app must be supported by a robust infrastructure that provides access to financial instruments and ensures a seamless user experience. The easier it is for an investor to enter the market, the greater the potential for expanding the retail investment base.
ARKA — How do international interest rates and geopolitical risks affect the cost of borrowing in Armenia?
M. Margaryan — The Armenian market is not isolated from the global economy. The cost of borrowing is influenced by global interest rates, the geopolitical landscape, and how investors assess risk.
The yields on Armenian financial instruments include a risk premium. The yield on U.S. government bonds serves as one benchmark for assessing this premium, though the final rate is also shaped by other factors, such as the specific risks associated with an individual issuer and the terms of the offering.
In September, the Central Bank of Armenia raised its refinancing rate by 0.25 percentage points to 6.75%, in response to inflationary risks, including those stemming from the external environment. The decision exceeded market expectations.
Any shifts in the global economic landscape or the policies of major central banks can affect the cost of financing in Armenia. Regional risks, including developments concerning Iran and the broader Middle East are also significant for our country.
ARKA — How do you envision the Armenian corporate bond market three to five years from now? Will it be able to become a significant source of business financing and attract foreign investors?
M. Margaryan — We are already working on expanding our international ties, offering corporate bonds from Armenian issuers to partners in the U.S., the U.K., Europe, the Middle East, and the broader region.
I do not believe that corporate bonds will overtake banking products within five years. However, I do expect significant market growththe total volume could potentially double.
I also anticipate growing interest in Armenian corporate bonds from investors in neighboring countries and the wider region. Over the next five years, we may well see new international capital flowing into specific bond issues.