YEREVAN, September 17. /ARКА/. The Central Bank of Armenia’s increase in the monetary policy rate to 6.75% does not automatically and immediately lead to higher rates on bank loans and deposits. However, if monetary policy tightening continues, the cost of bank funding may also change.
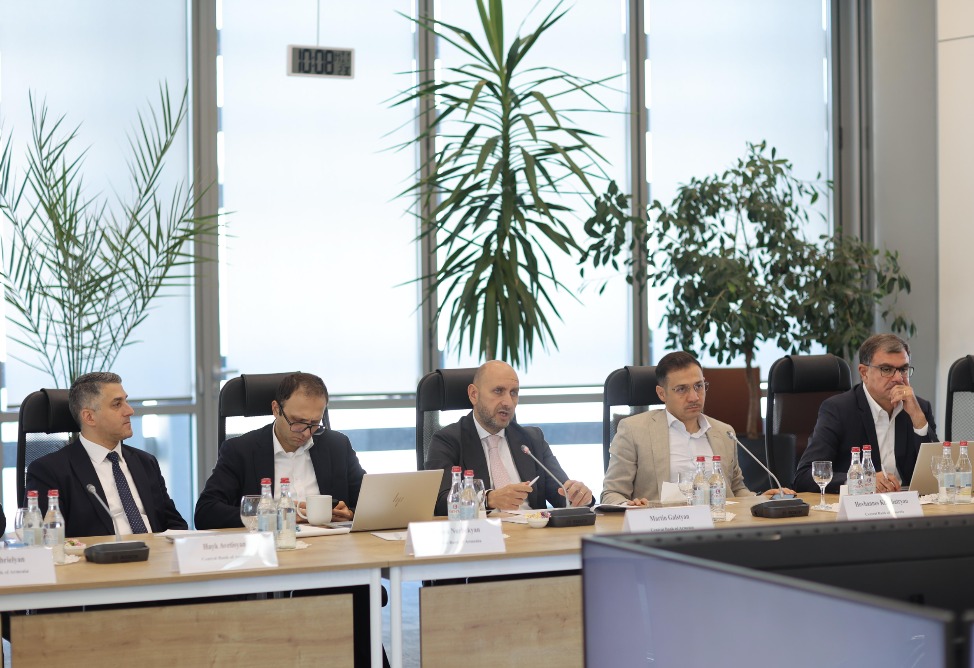
Central Bank of Armenia Chairman Martin Galstyan announced this following the Regulatory Council meeting on September 15.
The Central Bank Council raised the rate by 0.25 percentage points, from 6.5% to 6.75%. The Lombard repo rate was set at 8.25%, and the rate on funds attracted by the Central Bank from banks was set at 5.25%.
This is the first rate increase in more than three years.
Why loans don’t become more expensive the next day
The key interest rate is one of the benchmarks for the cost of money in the financial system, but there are several intermediaries between the Central Bank’s decision and the rate seen by bank clients.
The cost of a loan is influenced by a particular bank’s resource base, the cost of raising funds, the loan term, the borrower’s risks, competition between banks, and other factors.
Therefore, a 0.25 percentage point increase in the Central Bank’s interest rate cannot be automatically translated into a similar increase in rates on consumer, mortgage, or business loans.
Galstyan also pointed out that the monetary policy transmission mechanism operates with a time lag, and the speed of its action can vary.
What will happen if the hike is not a one-off?
The situation could change if the September decision marks the beginning of a longer period of monetary tightening.
Galstyan stated that if the current situation proves not temporary, but a trend, and the cycle continues, higher interest rates in Armenia should be expected.
This is a fundamental condition: the Central Bank has not yet announced the start of a rate hike cycle.
Moreover, the regulator continues to consider both scenarios.
Scenarios A assume stronger domestic and external demand and the risk of increased inflation expectations, which requires a higher rate trajectory. Scenarios B are associated, in particular, with a possible weakening of global growth and disinflationary risks and assume a lower rate trajectory.
What is happening with lending rates now?
The September hike itself occurred after a prolonged period of monetary easing.
However, it is incorrect to compare the change in the Central Bank rate with bank lending rates on a day-to-day basis. Data on bank lending costs reflect transactions already completed and depend on the currency, term, borrower category, and loan type.
Therefore, the practical impact of the September decision is more accurately assessed based on the subsequent dynamics of comparable bank interest rates in the Central Bank’s statistics.
What about deposits?
The Central Bank’s rate hike may eventually impact banks’ cost of raising funds, but the September 15 decision does not necessarily indicate a rise in deposit rates.
The decisions of individual banks depend on their resource needs, liquidity, deposit maturities, and the competitive situation.
Therefore, the practical impact of the September decision will become clearer once bank rate statistics for the following months are released.
What is known and what is not yet known
Known: The Central Bank raised the rate from 6.5% to 6.75%.
Known: The head of the Central Bank allows for higher bank interest rates if monetary policy tightening continues.
It is not yet known whether the September 15 decision will mark the beginning of a new rate hike cycle.
It is not yet known how much and when interest rates on specific types of loans and deposits will change.
The dynamics of these indicators will be one of the indicators of how quickly the Central Bank’s September decision is being processed through the Armenian financial system.
ARKA Data & Analytics